All Categories
Featured
Essential Final Expense or Burial Insurance Options
Reviewing New Life Insurance Benefits for Veterans
Comparing HMO Network Access versus Costs
Table of Contents
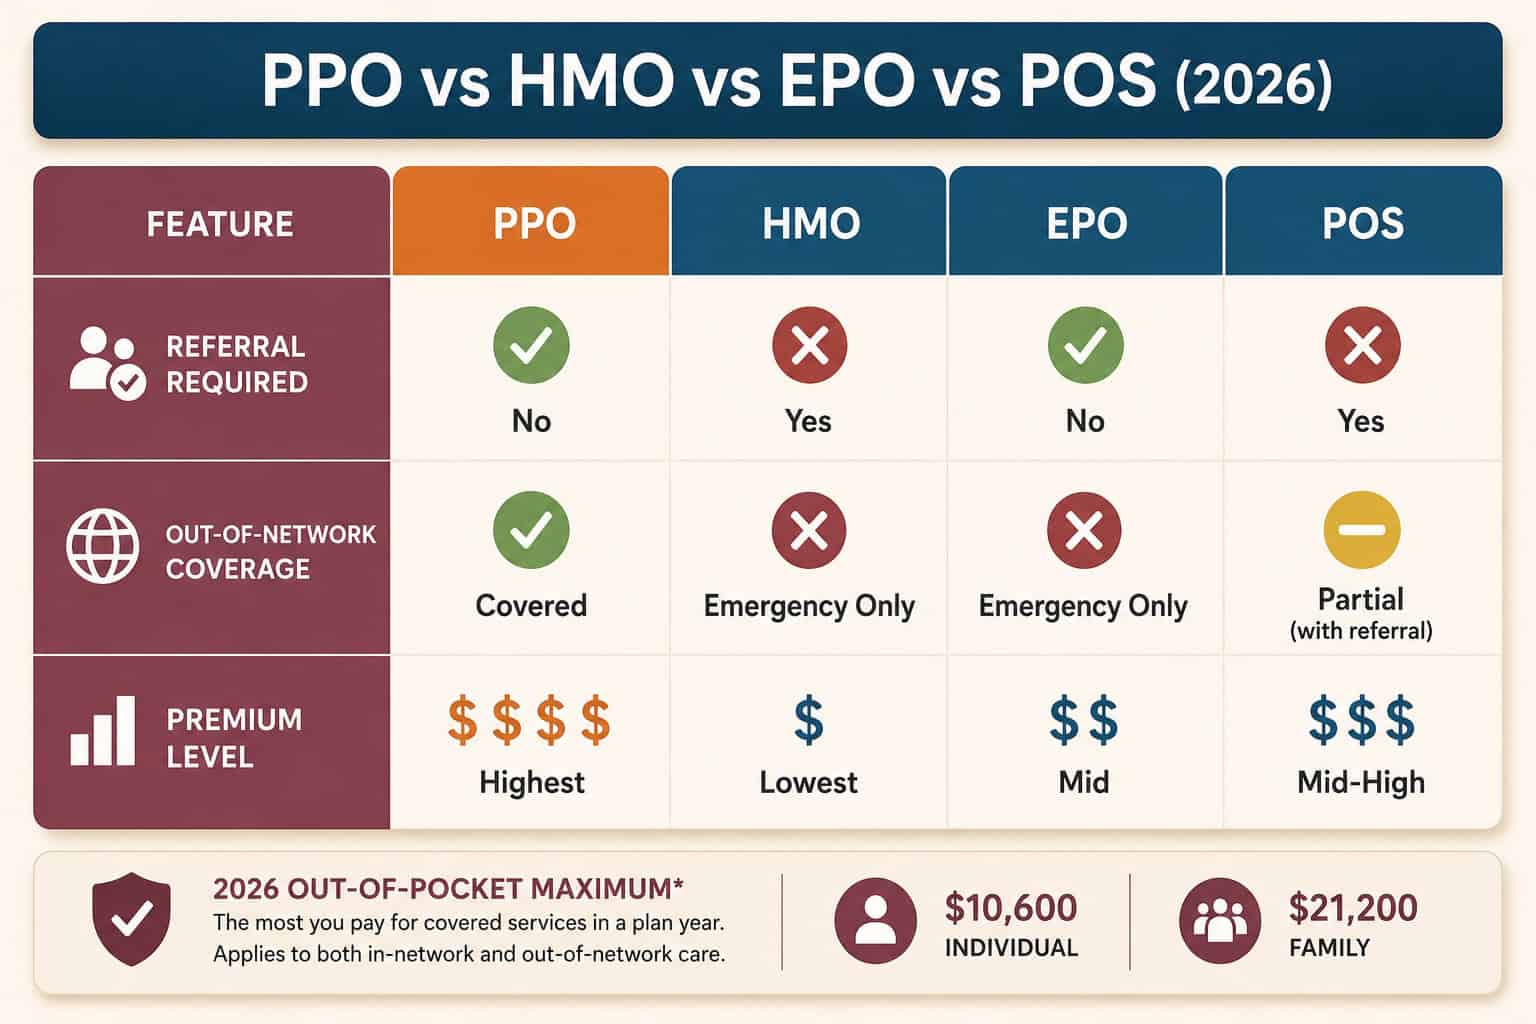
An HMO Medicare Advantage strategy offers a network (referred to as an "HMO network") of health care service providers and hospitals to its customers. It's required for a patient to select a main care physician to manage their healthcare and provide recommendations to any suppliers that are not in the strategy's network, except in the event of an emergency situation.
The ease of having a main care medical professional to collaborate and manage the care offered. A patient can only see suppliers within the plan's network unless they have a recommendation for an outdoors expert, or it's an emergency circumstance.
Unlike an HMO plan, a PPO Medicare Benefit plan allows for more flexibility when seeing out-of-network companies. It's not required to have a referral to see an out-of-network specialist although it may be more expensive and take extra time to get insurance coverage given that a patient should submit a claim for protection each time they see an out-of-network supplier.
The client has more flexibility with which suppliers they pick to see, whether they're within the strategy's network or out-of-network. Most times, there is no requirement for a referral if a client cares to see an out-of-network professional. Greater regular monthly premium. More than likely, greater monthly premiums. The client is accountable for managing their healthcare rather of a main care provider.
An EPO insurance strategy, or an 'Special Service provider Company' insurance plan, is typically called a strategy that is "located between an HMO and PPO." This is because, like a PPO plan, an EPO does not need a client to remain in-network for care significance, no recommendations or emergencies are essential for seeing an out-of-network supplier.
Analyzing PPO Provider Flexibility versus Monthly Costs
Although this strategy is less commonly understood, it frequently offers a much larger network than an HMO.A POS insurance coverage strategy, or a 'Point of Service' insurance coverage plan, is also understood to "blend aspects of HMO and PPO strategies." This is because, like an HMO strategy, a POS insurance plan needs a client to have a main care medical professional that manages their healthcare and offers them recommendations to out-of-network professionals or service providers.
, the deductible is at least $1,400 for a specific and $2,800 for a household. In order to fight the high deductible cost, it is advised that a patient contributes to an HSA/HRA or a 'Health Cost Savings Account'/'Health Compensation Arrangement,' which employers often contribute to yearly.
Another element to keep in mind about this plan is that it safeguards the client from "disastrous out-of-pocket expenditures for covered services." What this suggests is that, once a patient's "yearly out-of-pocket costs for covered services from in-network providers, consisting of deductibles, copayments, and coinsurance, reaches the fixed disastrous limit," the insurer will cover all expenses.
HMO and PPO plans share certain features. There are some main distinctions in between HMO and PPO strategies.
Understanding 2026 Medicare Enrollment Options and Seniors
HMOs will not cover care from an out-of-network service provider. PPOs will, however you'll likely save when you stay in network. HMOs normally have lower premiums and out-of-pocket expenses. PPOs might cost more, however they use more versatility.
When it comes to health insurance, you have your option of a number of plan types. Distinctions between HMO (Health Maintenance Company) and PPO (Preferred Provider Company) plans include network size, capability to see professionals, expenses, and out-of-network protection.
An HMO gives you access to particular physicians and healthcare facilities within its network. A network is made up of companies that have agreed to decrease their rates for plan members and also meet quality requirements. However unlike PPO strategies, care under an HMO plan is covered only if you see a provider within that HMO's network.

Latest Posts

Essential Final Expense or Burial Insurance Options

Reviewing New Life Insurance Benefits for Veterans
Securing Coverage to Support Families